Rent vs. Buy in Houston: Running the 2026 Numbers
A clear-eyed comparison of monthly costs, equity, and the break-even point in today's market.
September 24, 2026 | Raquel Refuerzo
Here is the thing nobody tells you when you ask "should I rent or buy in Houston right now": the answer changed in 2026. Prices softened, rents flattened, and mortgage rates landed in the mid 6s instead of the 7s. The gap between a rent check and a mortgage payment is now narrow enough that the decision comes down to one question. How long are you staying?
So let's skip the vibes and run the actual numbers for a Houston buyer today.
Quick Takeaways
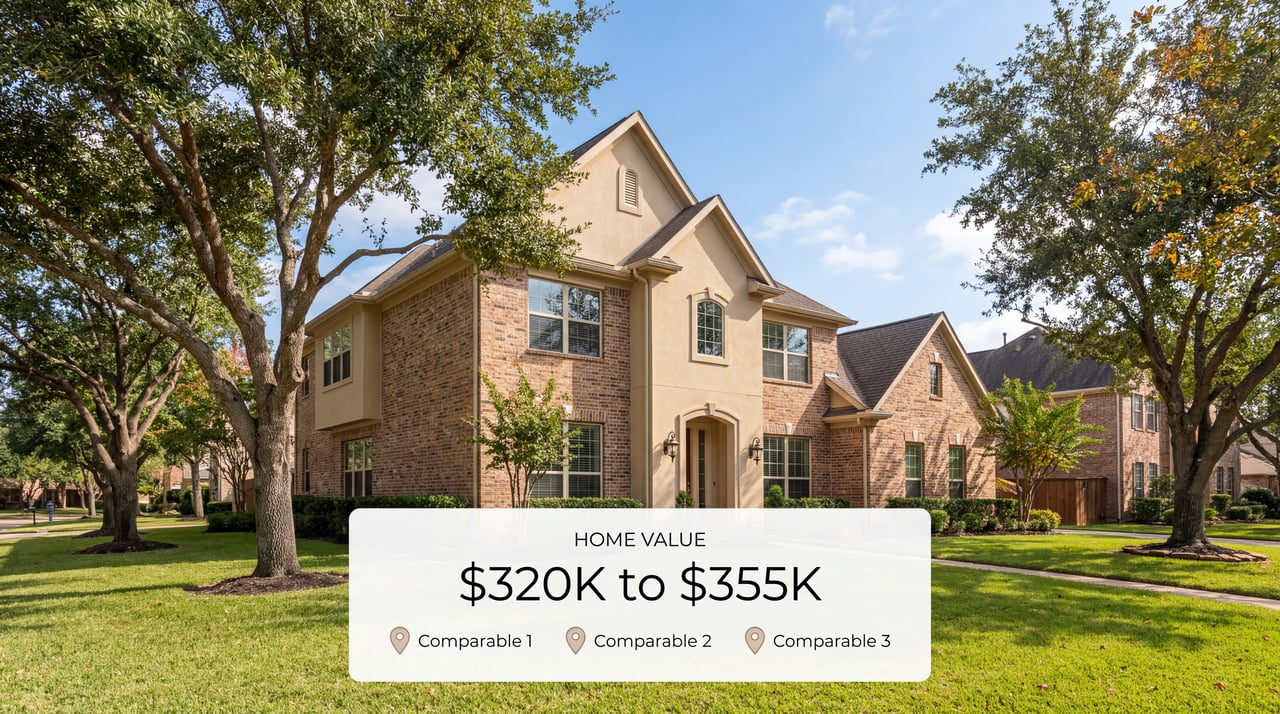
- The median Houston single-family home sits around $330,000 in 2026, down roughly 1.7% year over year.
- The average single-family rental runs about $2,050 a month. An apartment averages closer to $1,350.
- Owning the median home costs roughly $2,400 to $2,500 a month all in, so the monthly premium to own is about $400 to $450 over renting a comparable house.
- The break-even point right now leans toward 5 to 7 years, mostly because of round-trip transaction costs and flat prices.
- If you plan to stay 5-plus years, buying usually wins. Under 3 years, renting almost always does.
The Houston Numbers Right Now
You cannot make a smart rent-versus-buy call on national headlines, because Houston does not move with the national market. Here is where things actually stand in 2026.
The median single-family home price in the Greater Houston area is hovering around $330,000, down about 1.7% from a year ago. That is not a crash. It is a market that cooled, gave buyers more inventory, and handed back some negotiating power. For a full breakdown of what that means for purchasing power, our guide on how much house you can afford in Houston in 2026 walks through the math.
Mortgage rates have settled in the mid 6% range as of mid-2026, after dipping briefly into the high 5s earlier in the year before inflation pressure nudged them back up. Rates move weekly, so treat any single number as a snapshot. If you want to understand how even a half-point swing changes your budget, read how interest rates affect home buying in Houston.
On the rental side, the average lease for a single-family home in Houston is about $2,050 a month, actually down slightly year over year. Apartments average closer to $1,350, though that climbs fast in the Inner Loop. Rent stopped its post-pandemic sprint, which is good news for renters and an important data point for anyone weighing the trade.
The Monthly Math, Side by Side
Let's put real numbers on it. Take the median $330,000 home, 20% down, a 30-year fixed loan in the mid 6% range, and compare it to renting a comparable single-family home for $2,050.
Monthly cost | Buy ($330k, 20% down) | Rent (comparable home) |
|---|---|---|
Principal & interest | ~$1,670 | $0 |
Property taxes | ~$575 | $0 |
Homeowners / renters insurance | ~$250 | ~$20 |
Rent | $0 | $2,050 |
Maintenance & repairs (est.) | ~$275 | $0 |
Total monthly outlay | ~$2,770 | ~$2,070 |
Equity built in year one (principal paydown) | ~$240/mo | $0 |
Net monthly cost after forced savings | ~$2,530 | ~$2,070 |
So on paper, renting a comparable house costs you about $460 less per month right now. That is the real headline most "buying always wins" takes leave out. At today's rates, owning is not automatically cheaper month to month in Houston. What owning gives you is something rent never will. We will get to that.
A quick note on the down payment. Few buyers actually put 20% down. With 10% down, your loan is bigger, your principal and interest climb, and you add private mortgage insurance of roughly $100 to $150 a month. The upside is you only need about $33,000 instead of $66,000 to get in the door. First-time buyers should look at Houston first-time homebuyer programs before assuming they need a giant pile of cash.
What Renting Really Costs (and Doesn't)
Renting in 2026 is having a moment, and not in a bad way. Your monthly outlay is lower, your insurance is cheap, and your exposure to a leaky roof or a failed AC compressor in August is exactly zero. You also keep your flexibility, which matters more than people admit when their job, relationship, or plans are still in motion.
The cost renting hides is opportunity, not crisis. Every month you pay rent, you build zero equity. Your landlord can raise the rent at renewal. And you are not capturing any of the appreciation if Houston prices climb again. Renting is not throwing money away, that is a myth, but it is buying flexibility instead of ownership. Our deeper look at living in Houston as a renter vs. owner breaks down the lifestyle side of this trade.
What Owning Really Costs (and Builds)
Here is where Houston gets specific. Two line items make owning here pricier than buyers expect: property taxes and insurance.
Texas has no state income tax, so it leans hard on property taxes. Combined effective rates around Houston land near 2% or more of your home's value, which on a $330,000 home is roughly $6,600 a year before exemptions. File your homestead exemption and protest your appraisal every year. Our guide to Houston property taxes explains exactly how.
Insurance is the other one. Wind, hail, and flood risk push Houston homeowners insurance well above the national average, often $3,000 to $4,000 a year. If your home sits in a flood zone, add flood insurance on top. Never skip checking the map before you buy. Read flood zones in Houston: what buyers should know first.
Now the payoff. Every mortgage payment chips away at your loan, so roughly $240 a month in year one goes straight into your own equity instead of a landlord's pocket. That number grows every year as more of your payment hits principal. Add even modest appreciation and a fixed-rate payment that never rises while rents do, and ownership becomes a slow, forced savings account that pays you back when you sell.
The Break-Even Point: How Long Until Buying Wins
This is the whole game. Buying beats renting once your equity gains overcome two things: the roughly $460 monthly premium you pay to own, and the friction of getting in and out of a home.
That friction is bigger than most buyers realize. Closing costs to buy run about 2% to 5% of the price, so $7,000 to $16,000 on a $330,000 home. See our breakdown of closing costs for buyers in Houston. Then selling costs, including agent commissions and title fees, can run 6% to 8%, another $20,000 or more. You have to stay long enough for equity to cover that round trip plus the monthly gap.
The math shakes out like this:
- At flat prices (where Houston roughly is now), equity comes almost entirely from slow principal paydown. Break-even stretches to about 5 to 7 years.
- At 3% annual appreciation (Houston's longer-run norm), a $330,000 home gains close to $10,000 a year in value, pulling break-even down to roughly 3 to 4 years.
So the honest answer in 2026 Houston: if you are confident you will stay at least 5 years, buying very likely comes out ahead. If your horizon is under 3 years, renting almost always wins after you account for transaction costs.
When Renting Is the Smarter Move
Rent without guilt if any of these fit:
- You expect to move, change jobs, or relocate within 3 years.
- You do not yet have a stable down payment plus a cushion for closing costs and an emergency fund.
- You want zero maintenance responsibility and predictable monthly costs.
- You would rather invest the down payment and the monthly difference elsewhere, and you will actually do it.
Flexibility has real financial value. In a market where the monthly gap favors renting, staying liquid is a legitimate strategy, not a consolation prize.
When Buying Is the Smarter Move
Buy with confidence if these are true:
- You plan to stay at least 5 years, ideally longer.
- Your income is stable and your monthly housing cost would sit comfortably within budget.
- You want a fixed payment that does not rise every renewal the way rent does.
- You value building equity and want the option to make the place yours.
Today's softer prices and added inventory mean buyers have more leverage than they have had in years. Sellers are more willing to negotiate on price, closing costs, and rate buydowns. If a higher payment is the only thing holding you back, look at how to lower your mortgage rate or monthly payment before ruling buying out.
Run Your Own Numbers
Averages are a starting point, not your answer. Before you decide, get honest about four things:
- Your real timeline. Not your ideal one. How long will you actually live there?
- Your full monthly cost of owning. Use the table above, then plug in your target neighborhood's taxes and insurance, which vary a lot across Houston.
- Your total cash to close. Down payment plus closing costs plus a maintenance reserve.
- What you would do with the difference. If renting saves you $460 a month and you invest it, that changes the comparison. If it disappears into lifestyle, owning's forced savings wins by default.
When you are ready to compare against your actual budget and neighborhood, our piece on whether you should rent or buy in Houston right now is a useful next read.
The Bottom Line
In 2026, Houston's rent-versus-buy decision is genuinely close on a monthly basis, closer than it has been in years. Renting a comparable home costs about $460 less per month at today's rates. But that monthly edge flips the longer you stay, because ownership quietly builds equity while rent builds nothing for you.
The number that decides it is not the price, the rate, or the rent. It is your timeline. Under 3 years, rent. Over 5 years, buy. In between, run the math on your specific home, your specific neighborhood, and your specific plans. That is exactly the kind of analysis I do with clients every week, so the decision is based on your numbers, not a national headline.
Related Keywords: rent vs buy Houston, is it cheaper to rent or buy Houston, Houston rent vs buy calculator, should I buy a house Houston 2026, renting vs owning Texas